


… if your kids had a good chunk of money to help cover a down payment?
The Kinder Way Podcast – Season 3, Episode 1
The information provided in The Kinder Way Podcast is for educational purposes only, and is not intended as a substitute for professional advice from a licensed advisor. The content of each episode is the opinion of the host and interviewees, and does not represent the views of Serenia Life Financial or any of its other subsidiaries or affiliates. Please always consult a licensed insurance advisor for guidance. Serenia Life Financial does not endorse any third-party views referenced in this content.
“How would you feel if your kids had a good chunk of money towards a down payment?”
We’re back with Season 3 of The Kinder Way Podcast! In our first episode, our host sits down with one of her oldest friends to chat about something they’ve never really discussed before: Life insurance for kids! She’s surprised to learn that her friend is on the ball when it comes to investing in her children’s future. Tune in to find out what she did years before our host even knew about it!
Episode Transcript
Kathleen
On today’s episode of the Kinder Way podcast, I’m super excited that my oldest friend, Karen, joined me for a mom-to-mom chat. When I say oldest friend, I mean I’ve known Karen since we were both only six years old. Today, Karen is married and busy working and raising two little kids with her husband, Marty. Outside of work, Karen enjoys travel and trying new restaurants, and Marty is a volunteer basketball coach. While Karen and her family live about five hours away,
We try our best to get in a visit about once a year, so our kids have been in each other’s lives since they were born, which I love. During our chat, I learned that when her kids were both still just babies, Karen was lucky to have someone in her life encourage her to get life insurance for them. So in that sense, they are set. Before we get started, I should note that we are both speaking from personal experience and that this episode should not be taken as advice for your unique situation. Alright, let’s jump right in.
Kathleen (01:33)
So the thought of getting life insurance for your kids, your children, how does that make you feel? Do you think it’s necessary? Do you have it rhythm?
Karen (01:43)
I did get life insurance for my kids when they were born. I can’t even remember who advised us to do that, but we did it. And I felt I didn’t think it was necessary because I just thought like they’re so far away from having to worry about that kind of thing until somebody explained to me that if you don’t get it from the get-go, if anything ever happens and your kids end up with some sickness or whatever happens, then you might not get coverage for them. So of which I did I didn’t had no idea until I had kids. But yeah, we do have it.
Kathleen (02:13)
Hm, yeah. Yeah.
And do you are you aware of the investment component portion of their life insurance policy?
Karen (02:24)
I’m not.
Kathleen (02:26)
‘Cause with kids, because it’s a whole life policy, it comes with an investment component which grows over time. So
Karen (02:35)
Okay.
Kathleen (02:35)
Knowing that similar to their RESP, which is growing over time, and then they can use it for their education, this investment component within the whole life policy, which will grow over time, once they hit, let’s just say they want to buy a home at age 30, they could take that money out and possibly have enough money to pay a huge chunk of their damn payment. So if that is news to you, how does that make you feel?
Karen (03:01)
It is news to me and to me that would be sort of I think ideal because I think getting a down payment for a house is like the big b a big part of why people can’t buy homes these days. So if I could like eliminate that part for my kids and make sure they’re set up, that would be ideal.
I feel like they’re gonna be living with me until they’re thirty-five because I don’t think they’re gonna just with wages versus like cost of living and s I don’t think they’re gonna be able to move out at a young age like like you did, like I did or whatever. So yeah, I think they’re gonna be living with me.
Kathleen (03:33)
Yeah. Yeah. Well, if – I recommend looking into your policy, and your advisor, whoever your advisor is, can can do like a… Like obviously it’s not guaranteed, but they can kind of look to the future and see how much they would make by age twenty, twenty-five, thirty, forty-five. So they could
Karen (03:53)
Okay.
Kathleen (03:53)
…. have enough for let’s just say when they’re twenty, k to help with post-secondary, or when they’re twenty-five to travel the world, or when they’re thirty-two to pay for a damn payment. When they’re retiring, So there’s all these
Karen (04:03)
Right.
Kathleen (04:03)
… stages in life where this money can help them, right? So you got it for your kids when they were babies? Amazing.
Karen (04:09)
Yeah, as soon as they were born. And I wish I could remember who told us to do this, but it was based on the fact that like what if you have no idea what ailments your kids could have
Kathleen (04:15)
Yeah. Yes.
Karen (04:18)
… and it might exclude them from getting insurance. So get it before anything is ever detected. So that’s what we did.
Kathleen (04:24)
And it’s also like the absolute cheapest time to buy because as you age, insurance goes up and the price, right? Like I got
Karen (04:31)
Right.
Kathleen (04:31)
… it for I didn’t know about it. So I only found out once I got this job. So five years ago, I got the job. And then I think it was a year later as I was learning and educating myself. I’m like, my god, this is like a really smart thing to do for my kids. So I did it too, but I did it five years later than you. So my premiums are higher. Like I you yours has five extra years to grow in terms of that investment component. So like you’re real you’re really lucky. You’re sitting on a gold mine and you didn’t even know it. That’s funny. Okay, so considering Marty volunteers, is this year long that he does the basketball?
Karen (05:19)
It’s supposed to be just for the basketball season, but it tends to be more than that.
Kathleen (05:23)
Okay.
Karen (05:23)
I’ll say like a good nine months out of the year he’s participating in that. We get
Kathleen (05:26)
Yeah, it’s busy. Yeah.
Karen (05:28)
… a break over the summer.
Kathleen (05:29)
Gerry’s the same with soccer. It pretty much yeah, it’s pretty much all year that he’s spending at least, you know, two to three nights a week at practices or just driving from here to Hamilton. or like there’s always something and it keeps him busy, but he loves it. So how how do you think Marty would feel if he could get four hundred dollars a year back from his insurance company just because he volunteers in his community?
Karen (05:54)
I think he would be happy to get anything back out of it to help with the cost. Absolutely, yeah. Cause right now that’s not happening. So for sure any bit would help. Especially considering the time commitment. like a couple nights a week, sometimes three, four nights a week.
Kathleen (06:13)
Yes. It gets in the way of dinner plans, doesn’t it?
Karen (06:17)
Yes, it does.
Kathleen (06:19)
But it’s sweet. I do think it’s sweet, but it does it does disrupt things a little. is there anything that he does pay out of pocket for as like as a coach?
Karen (06:32)
Well the uniforms. He has to buy a uniforms when he does the reffing he has to fall in line with all the other refs and they have to have a specific attire when they or himself. Yeah, but that’s it. That’s the only thing that comes out of pocket. And then if he goes out of town, he is given an allowance. But again, there’s more that comes out of pocket because it doesn’t cover what is needed to be out of town to do this reffing.
Kathleen (06:59)
Right. And do you know how much like does he have to buy a new uniform every year, or is it just the one until it kinda wears up?
Karen (07:08)
I think it’s it’s just he has two of them and then
Kathleen (07:13)
Mm.
Karen (07:14)
… there’s like they have to show up wearing a certain outfit. They have to have this the shoes are replaced like a couple times a year ’cause they wear out. And then yeah, he has different pieces of the outfit. Some of them last longer than others, but they’re costly.
Kathleen (07:27)
Mm. I would I imagine yeah, I imagine that the four hundred would even just help well, I’m sure it’s not that much. But if you’re getting new shoes and new everything every few years like…
Karen (07:35)
Well, shoes are close to two hundred dollars when you’re buying like the the basketball shoes that they have to wear and yeah, so the four hundred
Kathleen (07:43)
Yeah, it’s crazy.
Karen (07:44)
… dollars would would help for sure.
Kathleen (07:47)
Yeah…
So there you go. You can’t beat a little kindness. And it goes to show when done right, insurance can be both human and kind.
Speaking of insurance, I’m ending this episode with an important disclaimer. When you heard me mention the investment component, I was referring to the cash value of a participating whole life policy, which will generally be reduced if you choose to access it via a withdrawal, policy loan, or surrender. If the policy loan isn’t paid back, the outstanding balance and interest will be subtracted from the death benefit, decreasing that final payout.
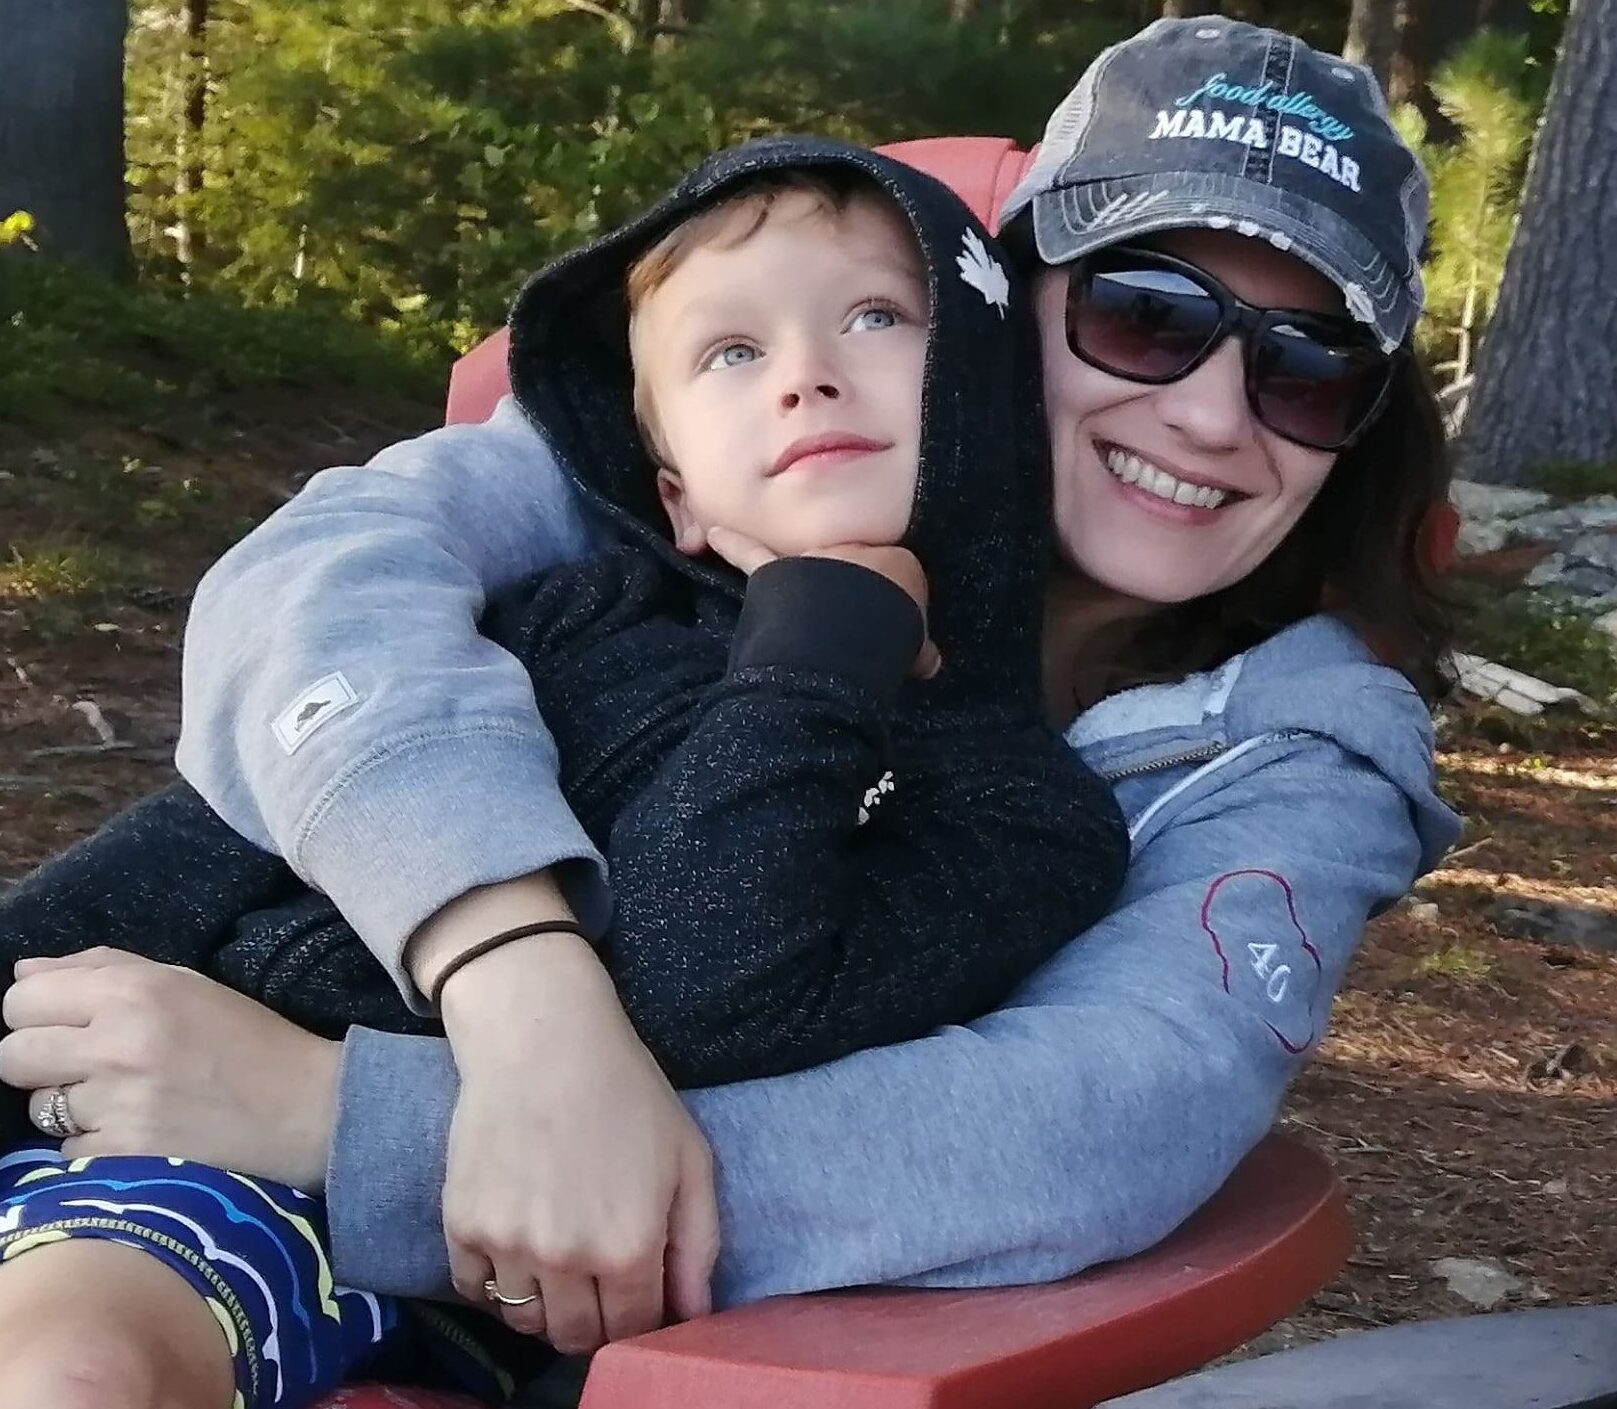
Meet our Host
Kathleen O’Hagan is the Digital Content Strategist & Writer at Serenia Life. She is married with one kid and two cats, and enjoys travel, discovering new restaurants, and idealizing life in the 80s and 90s. (Yes, she bought life insurance for her son – it’s an investment in his future! And yes, her pets are in her will.) See what else she has to say as host of the newly launched The Kinder Way Podcast.
